


How a three-digit score quietly shapes stress, self-worth, and financial confidence—and how to relate to it calmly
If checking your credit score makes your stomach tighten, you’re not overreacting.
For many people, a credit score doesn’t feel like data.
It feels like a judgment.
At LifeWellToday, we view credit score anxiety as a Financial Wellness issue, not a knowledge gap. This article explores why a simple number can feel so personal—and how to work with it clearly, without panic or shame.
Why Credit Scores Trigger Anxiety
A credit score is often treated as a shortcut for trustworthiness. Over time, this creates a powerful emotional association:
Good score = responsible, adult, safe
Low score = careless, risky, failing
Even though none of this is objectively true, the association sticks.
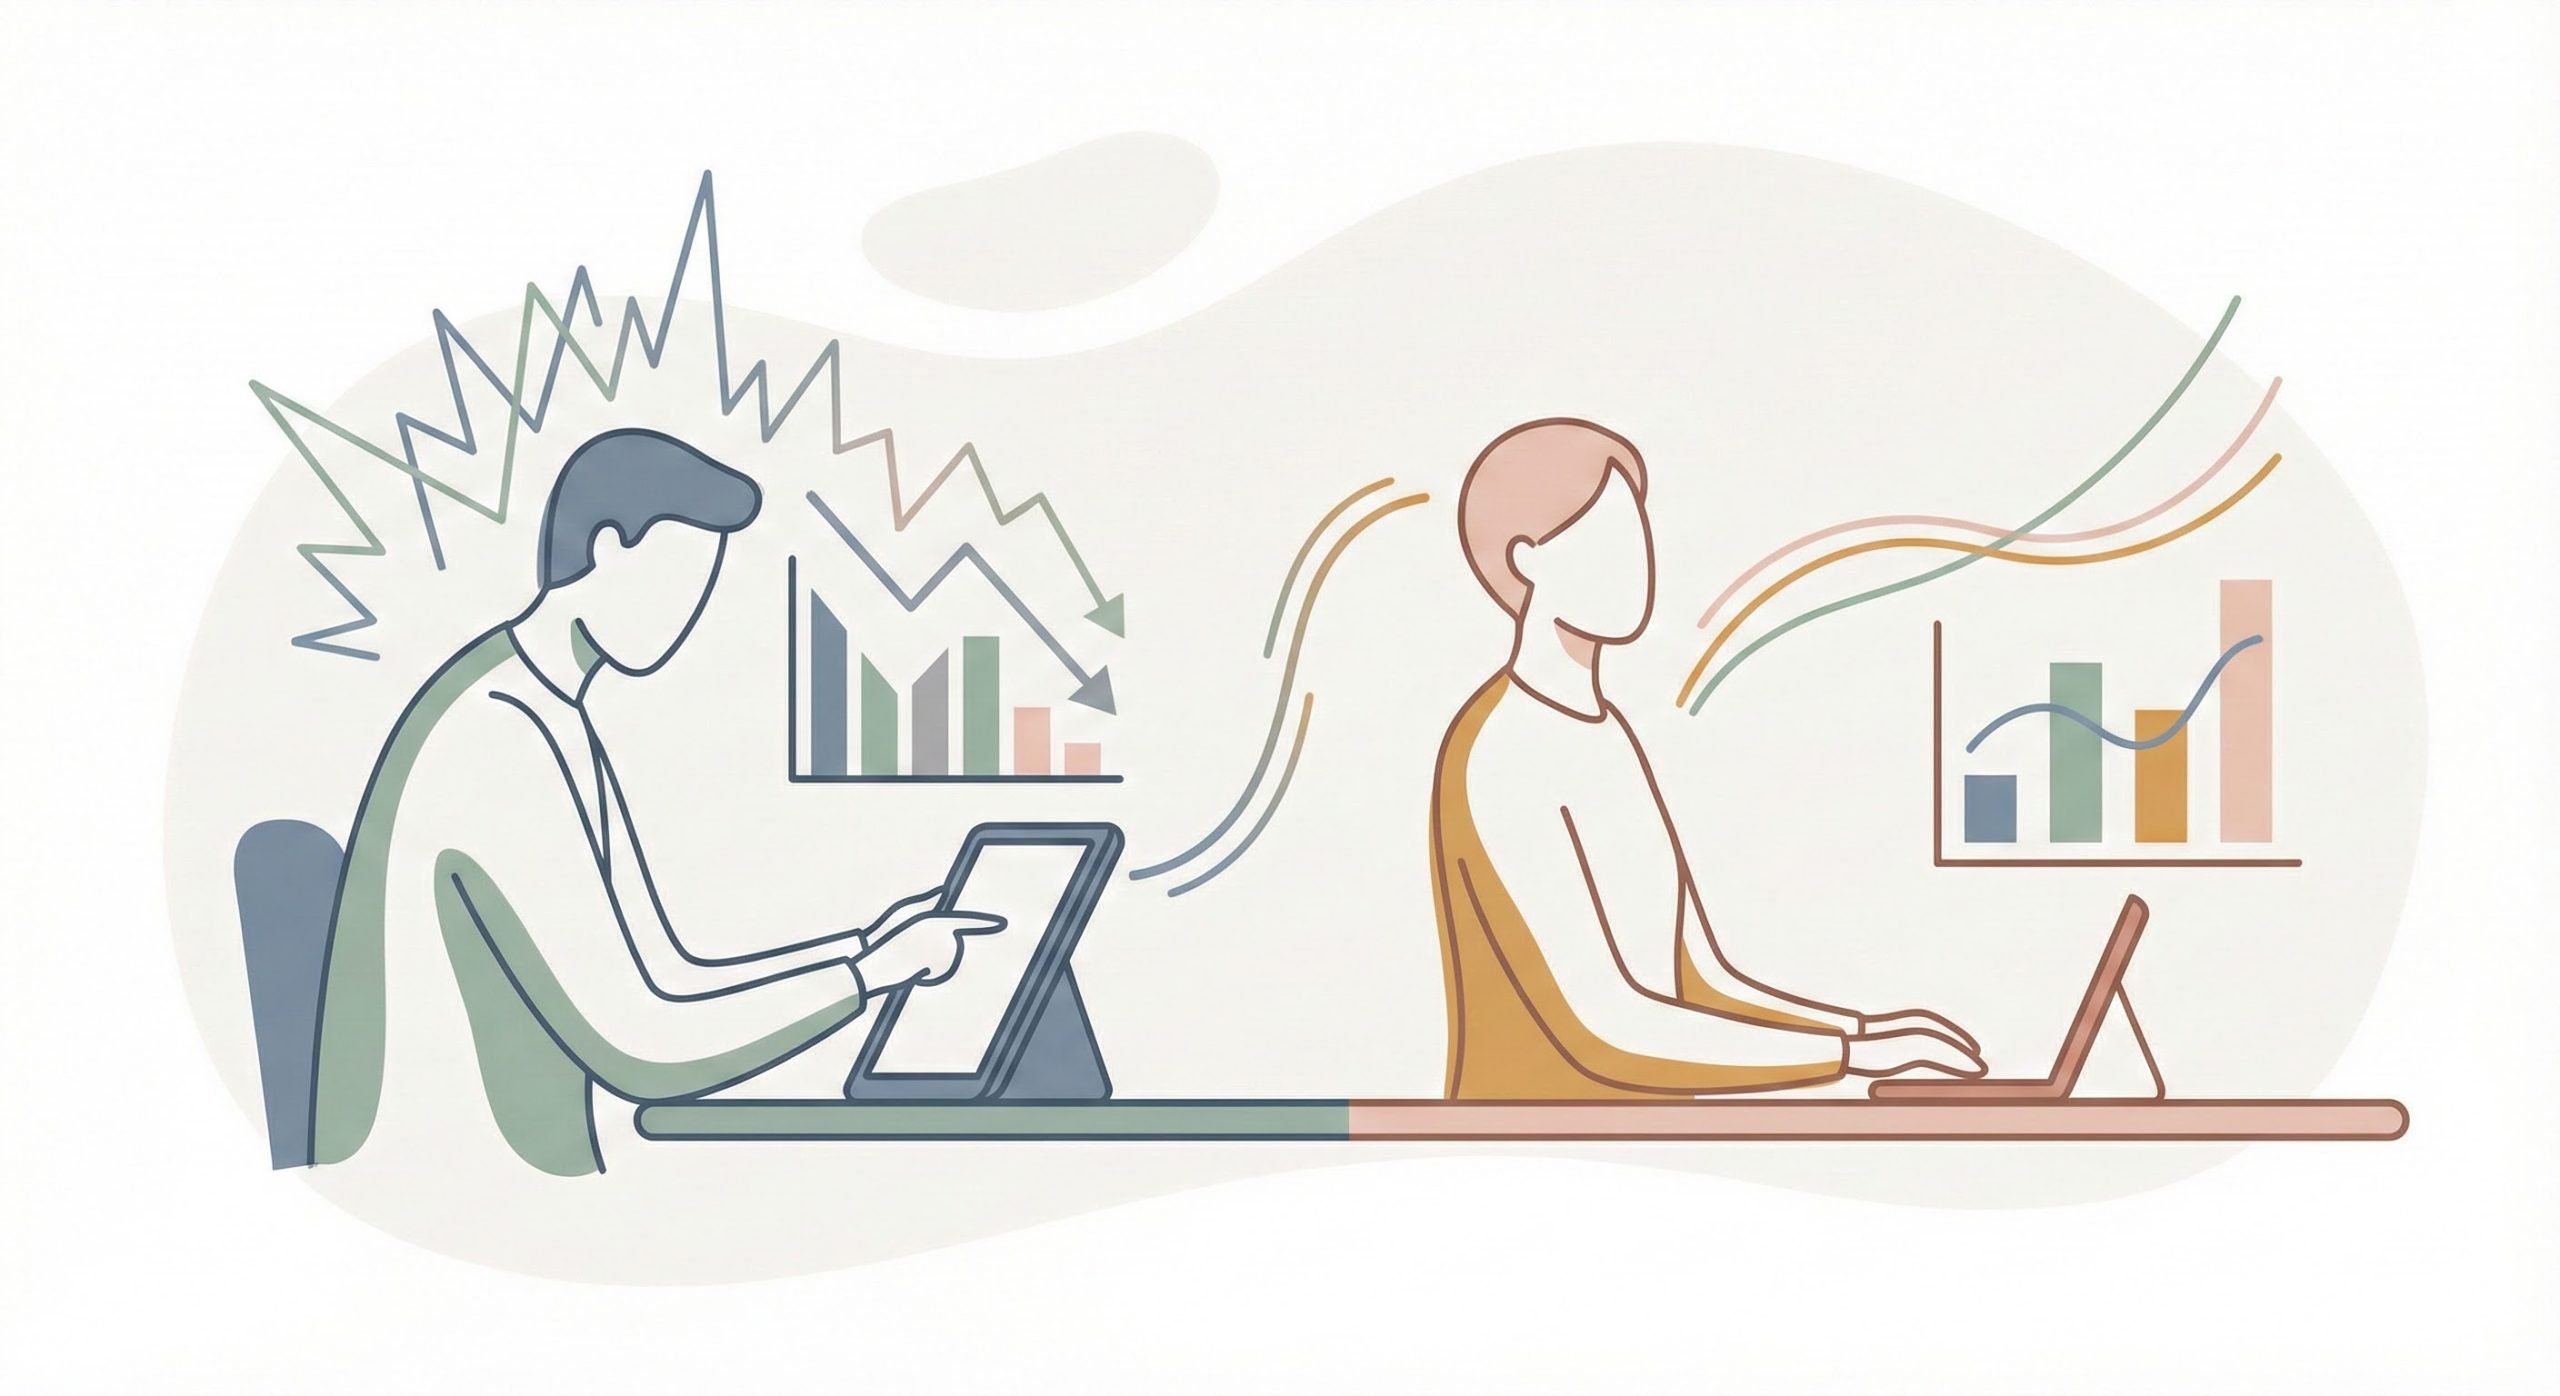
Your nervous system doesn’t read your credit score as information—it reads it as social risk.
The Hidden Psychology Behind Credit Score Stress
1️⃣ Credit Scores Mimic Social Ranking
Humans are wired to care about ranking and belonging. A credit score feels like a silent ranking system—one that determines access to housing, loans, and even opportunities.
This activates the same stress circuits as social rejection.
2️⃣ Credit Scores Compress Complex Lives Into One Number
A score can drop because of:
-
medical bills
-
temporary income loss
-
life transitions
-
one missed payment years ago
But the number doesn’t explain the story. It only reports the outcome—stripping away context.
That mismatch fuels shame.
3️⃣ Credit Scores Are Often Learned Through Fear
Many people first learn about credit through warnings:
-
“Don’t mess this up.”
-
“This will haunt you forever.”
Fear-based learning wires anxiety into the system early.
When Monitoring Turns Into Obsession
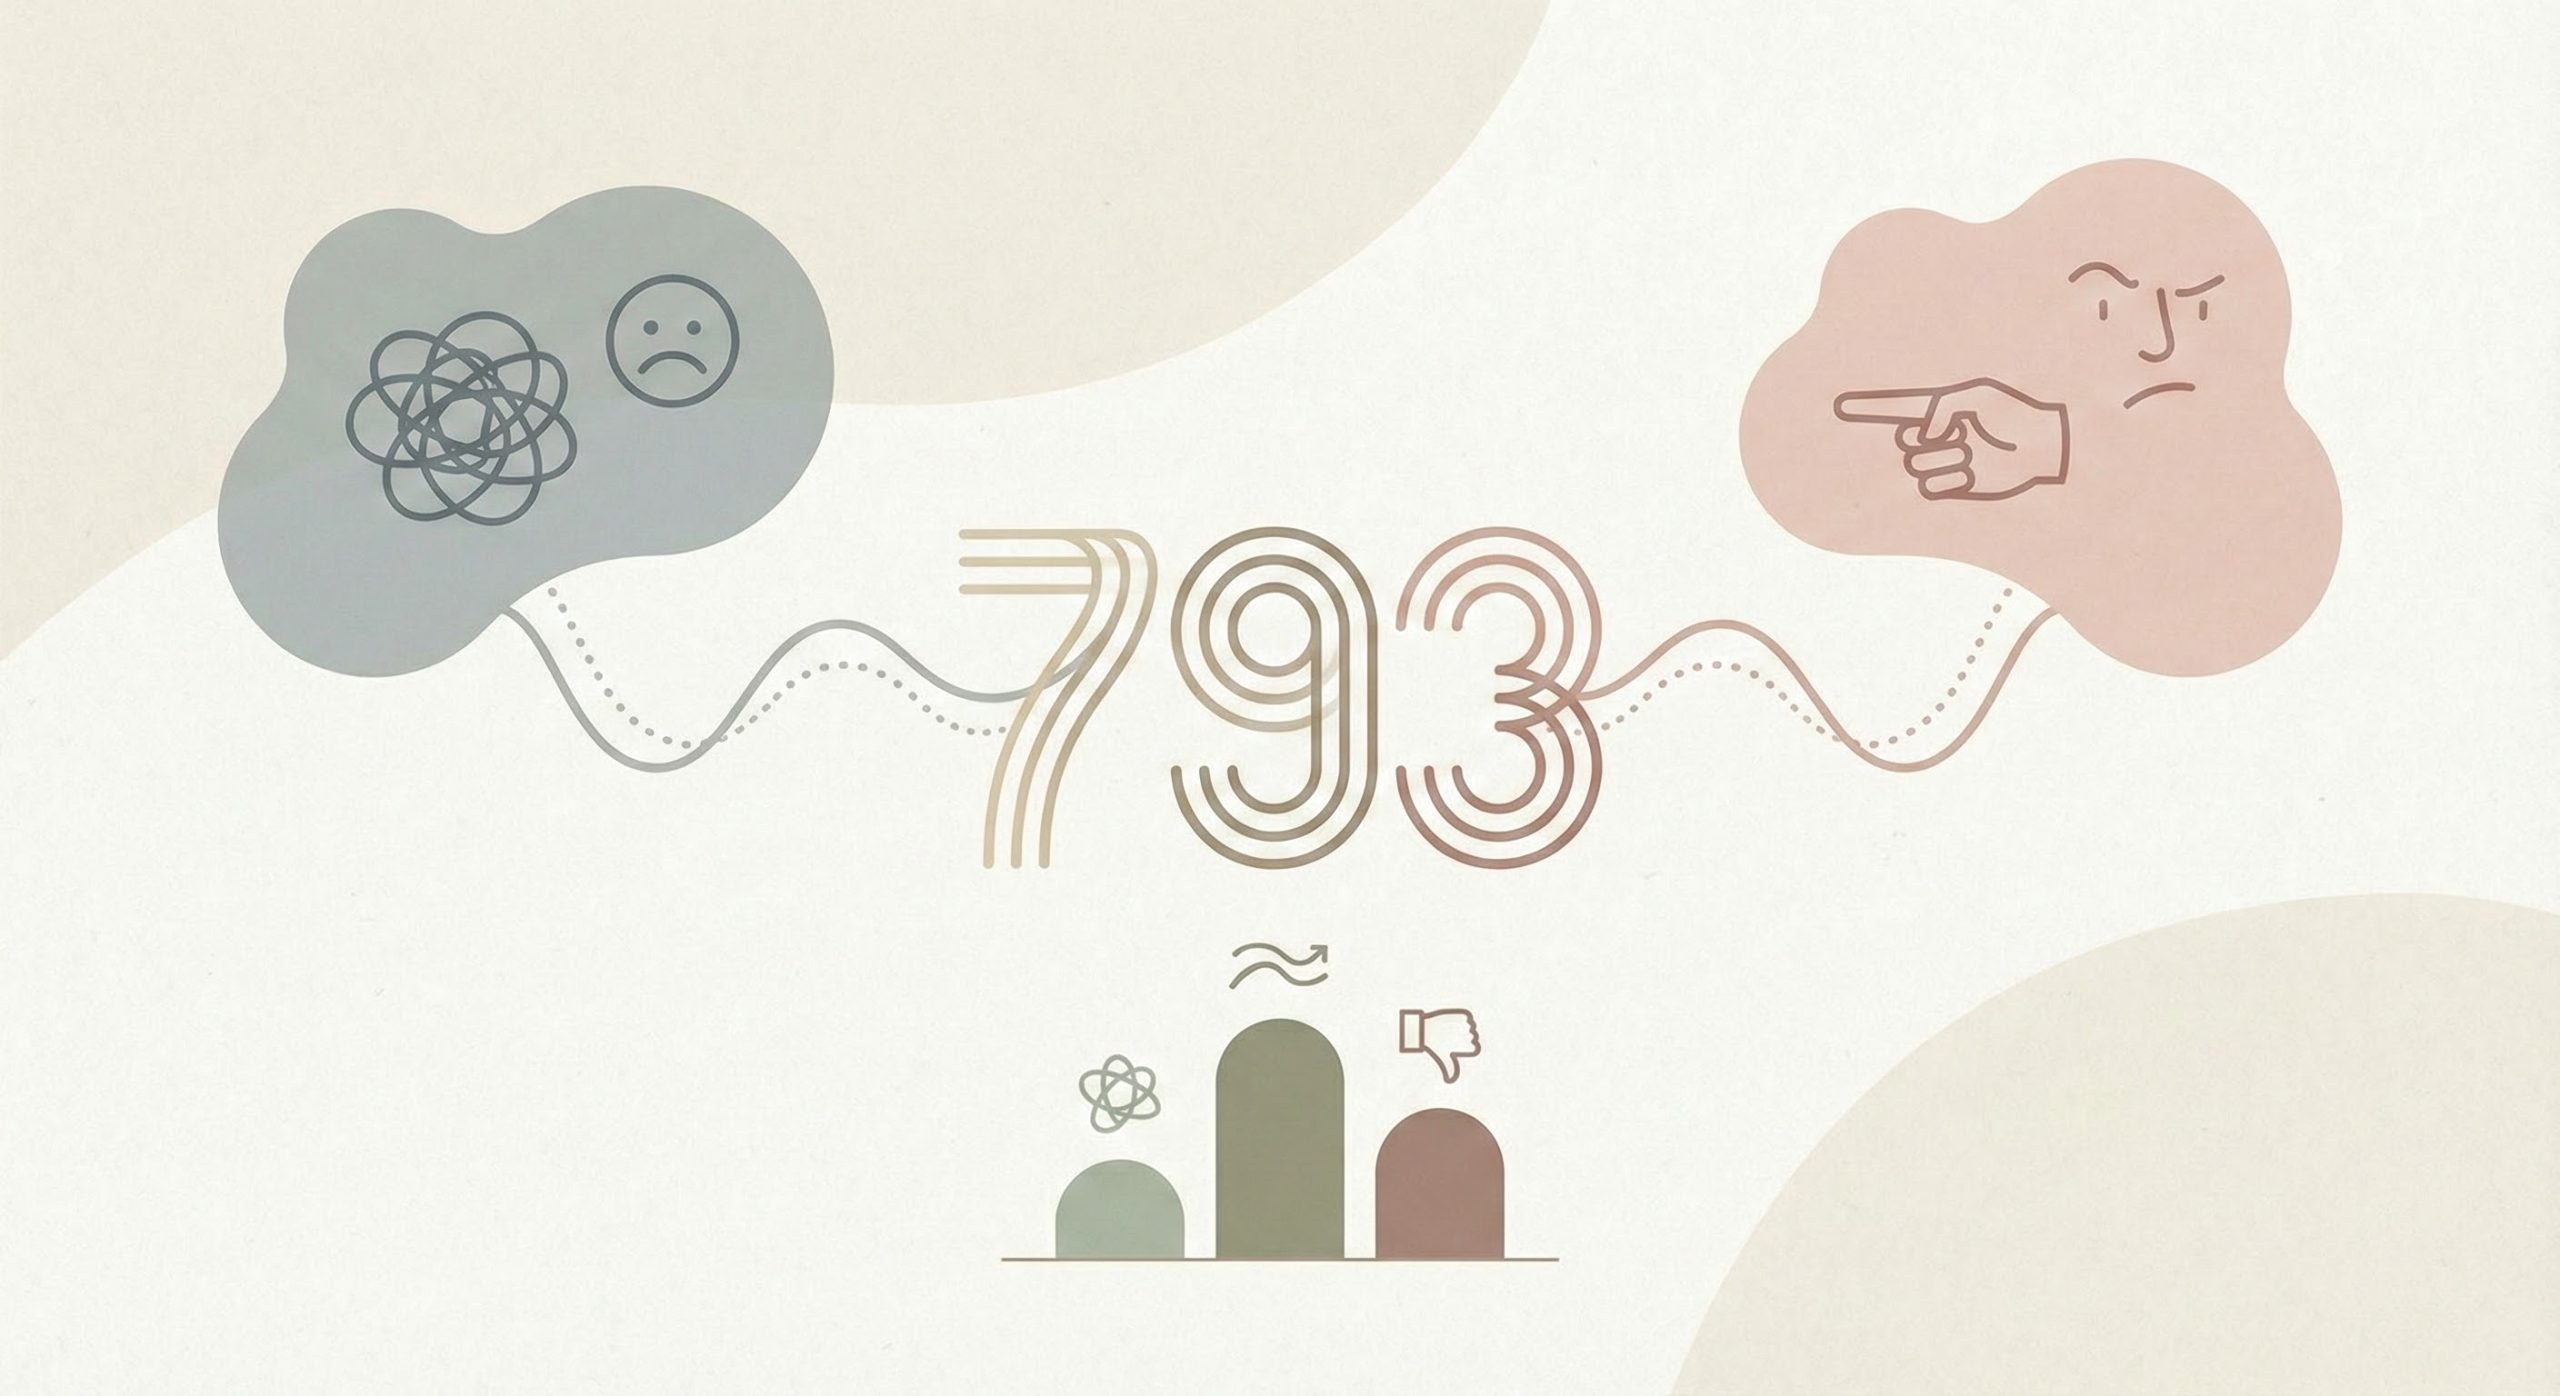
Some people cope by avoiding their credit score entirely. Others check it compulsively.
Both responses come from the same place: a desire to feel safe.
Obsession feels like control.
Avoidance feels like relief.
Neither actually builds calm.
Why Credit Score Anxiety Impacts Financial Wellness
Unchecked credit score stress can lead to:
-
hesitation around financial decisions
-
delaying applications or planning
-
reluctance to seek help or advice
-
constant low-level anxiety
Financial wellness requires emotional neutrality around information.
Reframing the Credit Score
A healthier frame:
Your credit score is a snapshot, not a verdict.
It reflects recent patterns—not intelligence, effort, or worth.
It is a tool, not an identity.
A Calm Way to Relate to Your Credit Score
1️⃣ Shift From Judgment to Data
Instead of asking:
“What does this say about me?”
Ask:
“What behavior does this reflect right now?”
This removes identity from the equation.
2️⃣ Limit Exposure
Checking too often increases anxiety without improving outcomes.
A calmer rhythm:
-
once every 1–3 months
-
no checking during emotionally charged moments
-
no immediate action required
3️⃣ Focus on Direction, Not Perfection
Credit scores respond slowly. Small, consistent actions matter more than rapid fixes.
Direction builds confidence.
Perfection fuels stress.
4️⃣ Separate Past Events From Present Capacity
A low score often reflects past constraints, not current ability.
You are allowed to grow beyond your financial history.
When to Seek Support
If credit score anxiety:
-
causes persistent stress
-
leads to avoidance or panic
-
blocks important life decisions
Support tools or credit counseling can help translate confusion into clarity—without judgment.
Clarity reduces fear.
Credit Scores and Self-Trust
The deeper work is not improving the number—it’s rebuilding self-trust.
Self-trust sounds like:
-
“I can face this calmly.”
-
“I can improve this over time.”
-
“This number doesn’t define me.”
That mindset is the foundation of sustainable financial wellness.
Gentle Reflection
-
When did your credit score start feeling personal?
-
What fear comes up first—judgment, rejection, limitation?
-
How would your relationship with money change if this number felt neutral?
Frequently Asked Questions
Is credit score anxiety common?
Yes—especially among responsible, high-functioning adults.
Does a low score mean I’m bad with money?
No. It reflects specific behaviors or events, not character.
Will worrying about my score improve it?
No. Calm, consistent actions—not stress—drive improvement.
Final Thought
A credit score is meant to measure risk—not worth.
When you stop letting a number speak for your value,
you regain the clarity needed to use it wisely.
Financial wellness begins when information stops feeling personal—and starts feeling manageable.
Continue the Financial Wellness Series
This article is for educational purposes only and does not constitute financial advice.
Sources
Consumer Financial Protection Bureau. Understanding credit reports and scores.
Experian. Credit education resources.
When to Seek Help
If credit concerns are causing distress or avoidance, a certified credit counselor can help you understand options and regain confidence.

Michael Tran
Financial Wellness Editor at LifeWellToday
About Michael Tran
Michael Tran is a Financial Wellness Editor at LifeWellToday, where he focuses on the intersection of money, mental well-being, and everyday life.
His work helps readers understand financial stress not as a personal failure, but as a natural response to modern pressures—rising living costs, healthcare expenses, workplace demands, and economic uncertainty. Michael writes with a calm, human-centered approach, translating complex financial and insurance topics into practical, emotionally grounded guidance.
Rather than promoting hustle culture or extreme financial optimization, Michael emphasizes clarity, emotional safety, and sustainable habits. His goal is to help readers feel more confident and less overwhelmed when making everyday financial decisions.
Areas of Focus
- Money anxiety and emotional stress around finances
- Insurance literacy (health, life, and workplace coverage)
- Financial boundaries at work and burnout-related money stress
- Emergency funds, medical bills, and financial avoidance
- Behavioral finance and habit-based money systems
All content is written to align with responsible YMYL standards, prioritizing education, balance, and reader well-being.
Editorial Approach & Standards
At LifeWellToday, Michael collaborates closely with the editorial team to ensure that all Financial Wellness content:
- Is educational and informational—not personalized financial advice
- Reflects evidence-based insights from reputable sources
- Avoids fear-based or urgency-driven messaging
- Aligns with Google’s E-E-A-T (Experience, Expertise, Authoritativeness, Trustworthiness) guidelines
When appropriate, articles include references to trusted public sources and guidance on when readers should seek professional financial, medical, or mental health support.
Experience & Background
Michael has experience in editorial research and long-form content development within the lifestyle and wellness space. His background includes analyzing behavioral patterns, simplifying complex topics, and building content systems designed for clarity and reader trust.
He believes financial wellness is not about perfection or wealth—but about creating a sense of safety, agency, and self-respect around money.
Disclaimer
Michael Tran is not a licensed financial advisor, medical professional, or legal expert. All content published on LifeWellToday is intended for educational and informational purposes only and should not be considered professional advice.
Readers facing serious financial, medical, or mental health concerns are encouraged to consult qualified professionals.
Contact & Editorial Inquiries
For editorial questions or content-related inquiries, please contact:
? michael@lifewelltoday.com