


A calm, practical guide to facing medical debt without fear, self-blame, or emotional overload
Medical debt carries a unique kind of stress.
It doesn’t feel like other debt.
It often arrives after illness, injury, or an emergency.
And it can quietly trigger shame—even when you did nothing wrong.
At LifeWellToday, we treat medical debt stress as a Financial Wellness issue, not a moral failure. This guide explains why medical debt feels so overwhelming and how to respond with clarity, dignity, and calm—without panic.
Why Medical Debt Feels Heavier Than Other Debt
Medical debt sits at the intersection of health, safety, and money. When those three collide, your nervous system reacts strongly.
Unlike consumer debt, medical debt is often:
-
unexpected
-
unavoidable
-
confusing
-
emotionally charged
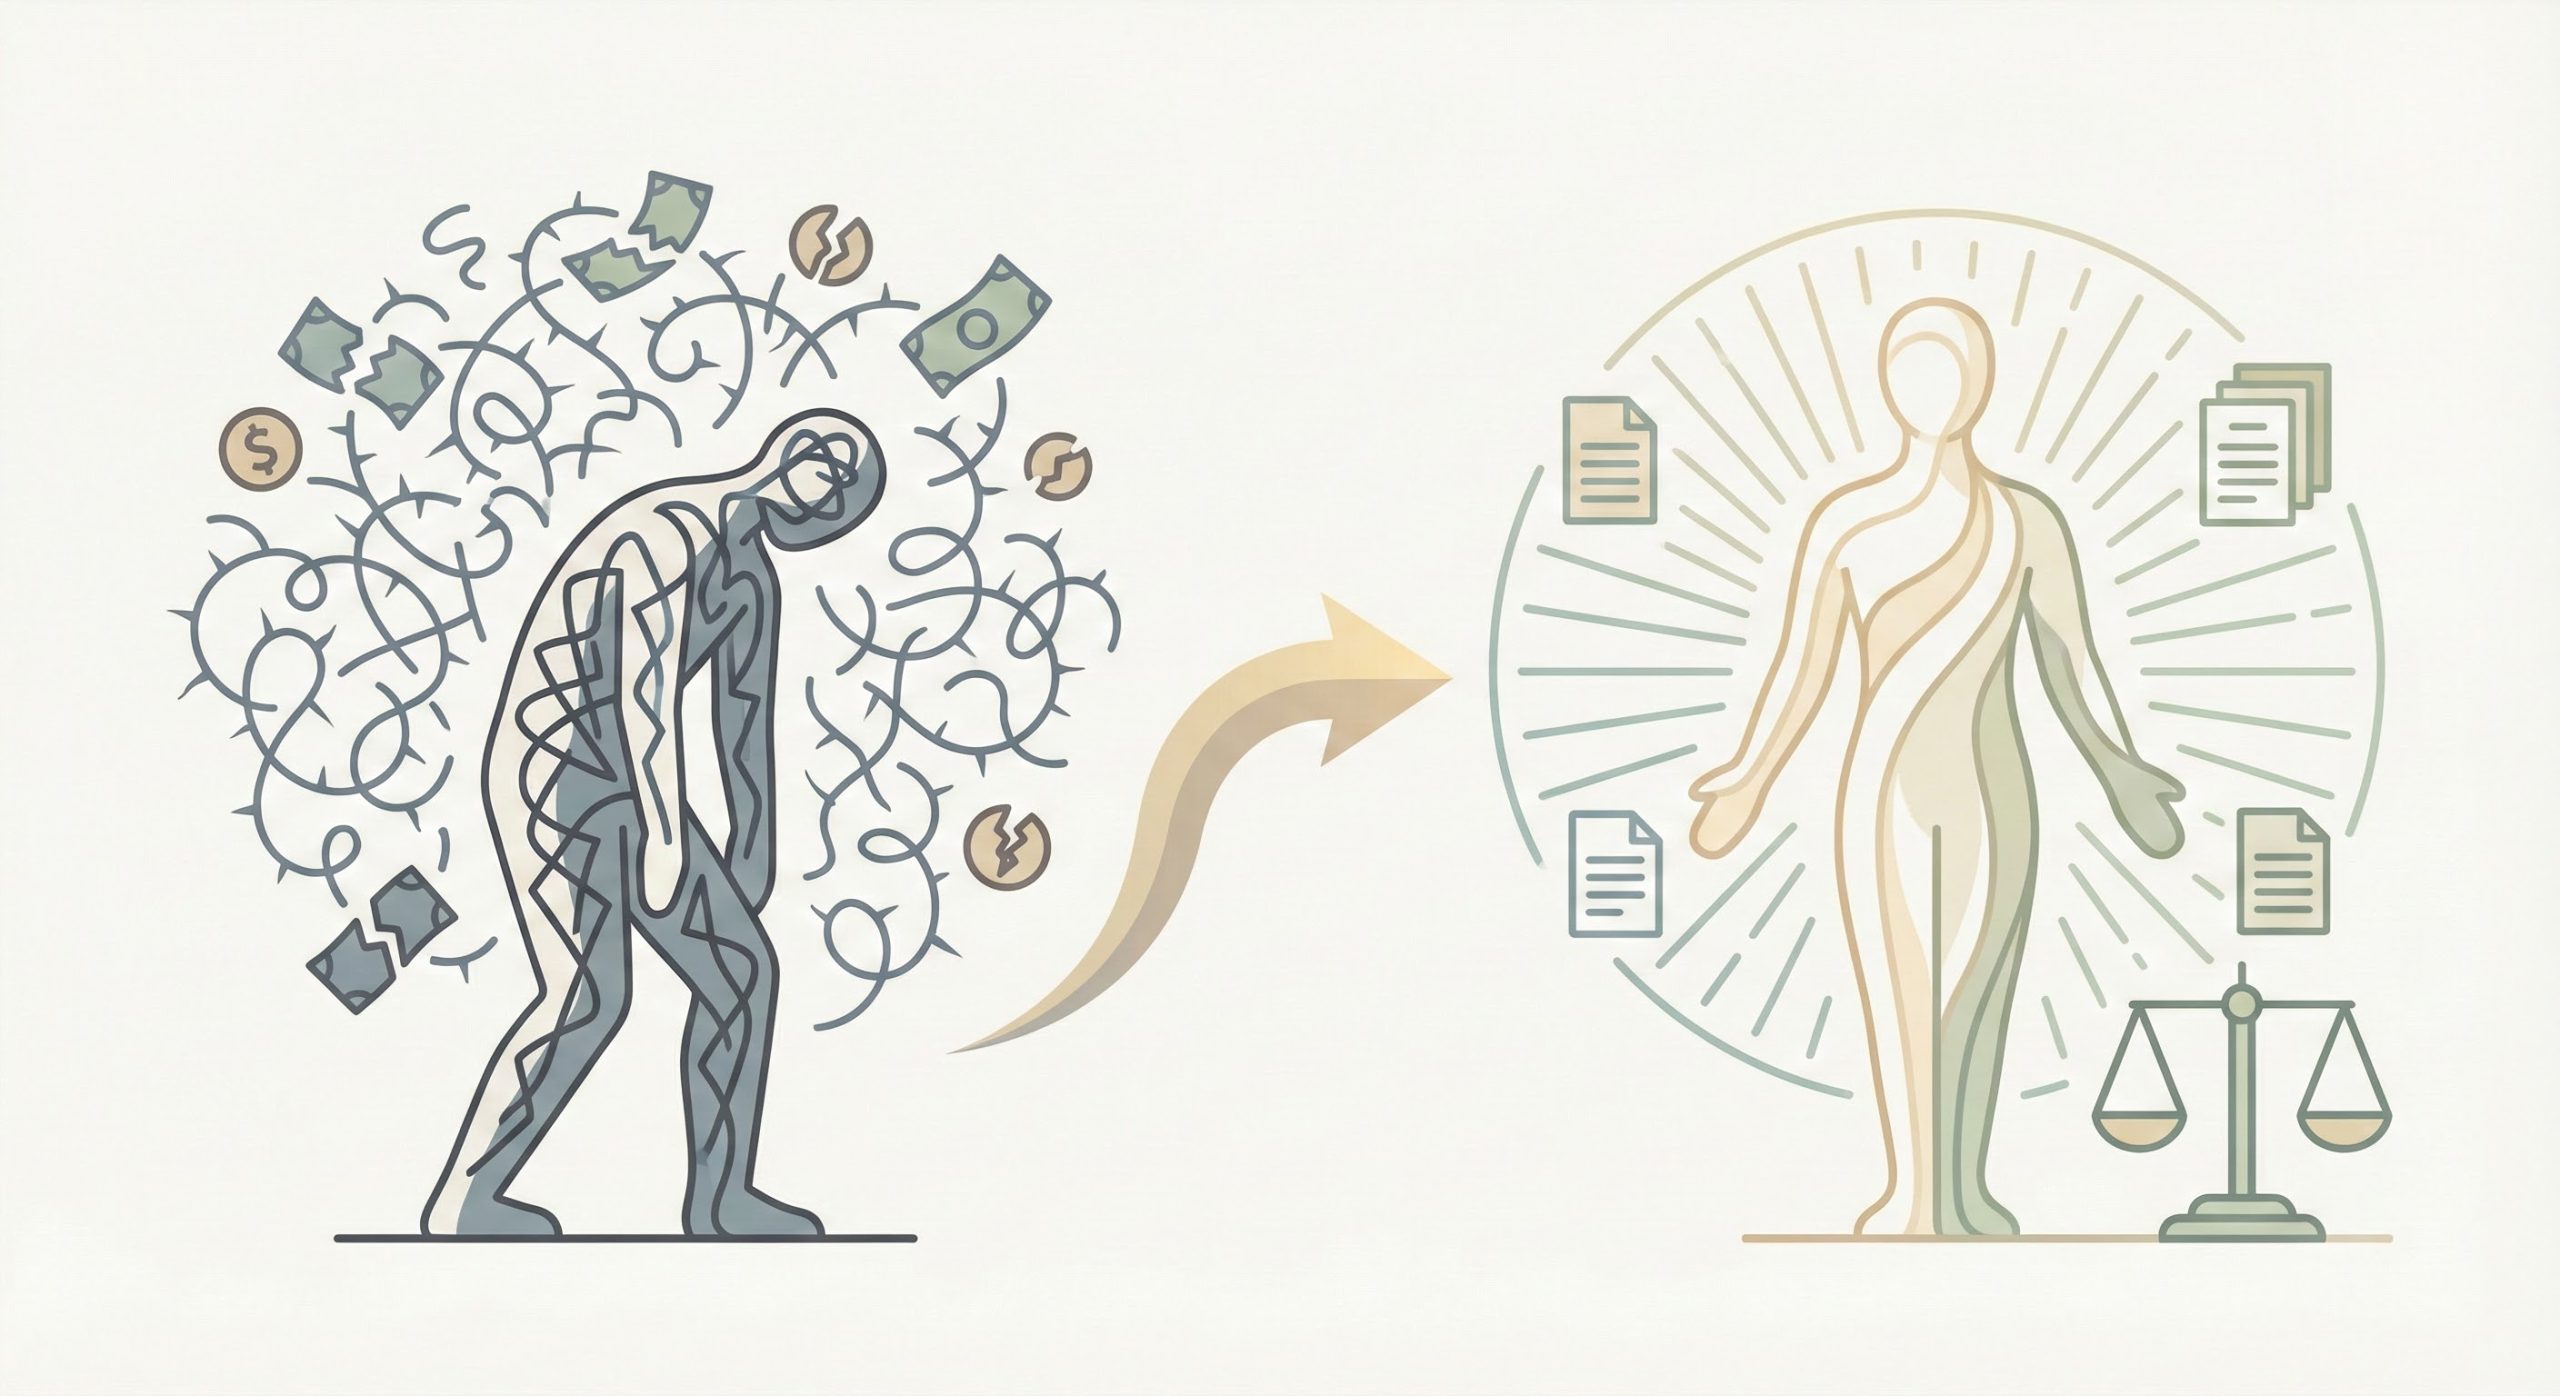
Your body doesn’t interpret it as a bill—it interprets it as threat.

The Hidden Emotional Layer: Shame
Many people feel ashamed about medical debt, even when the situation was out of their control.
Shame often sounds like:
-
“I should have planned better.”
-
“I must have done something wrong.”
-
“I shouldn’t be struggling like this.”
This emotional response makes the debt feel personal—even when it isn’t.
Why Shame and Panic Make Medical Debt Worse
When shame enters the picture, people tend to:
-
avoid opening bills
-
delay communication
-
miss options for flexibility
-
carry constant background anxiety
Panic narrows thinking.
Avoidance increases uncertainty.
Neither helps resolution.
Reframing Medical Debt (This Matters)
A healthier perspective:
Medical debt is not a reflection of responsibility or intelligence.
It is often a result of how healthcare systems work—not personal failure.
This reframe alone can reduce emotional pressure and restore clarity.
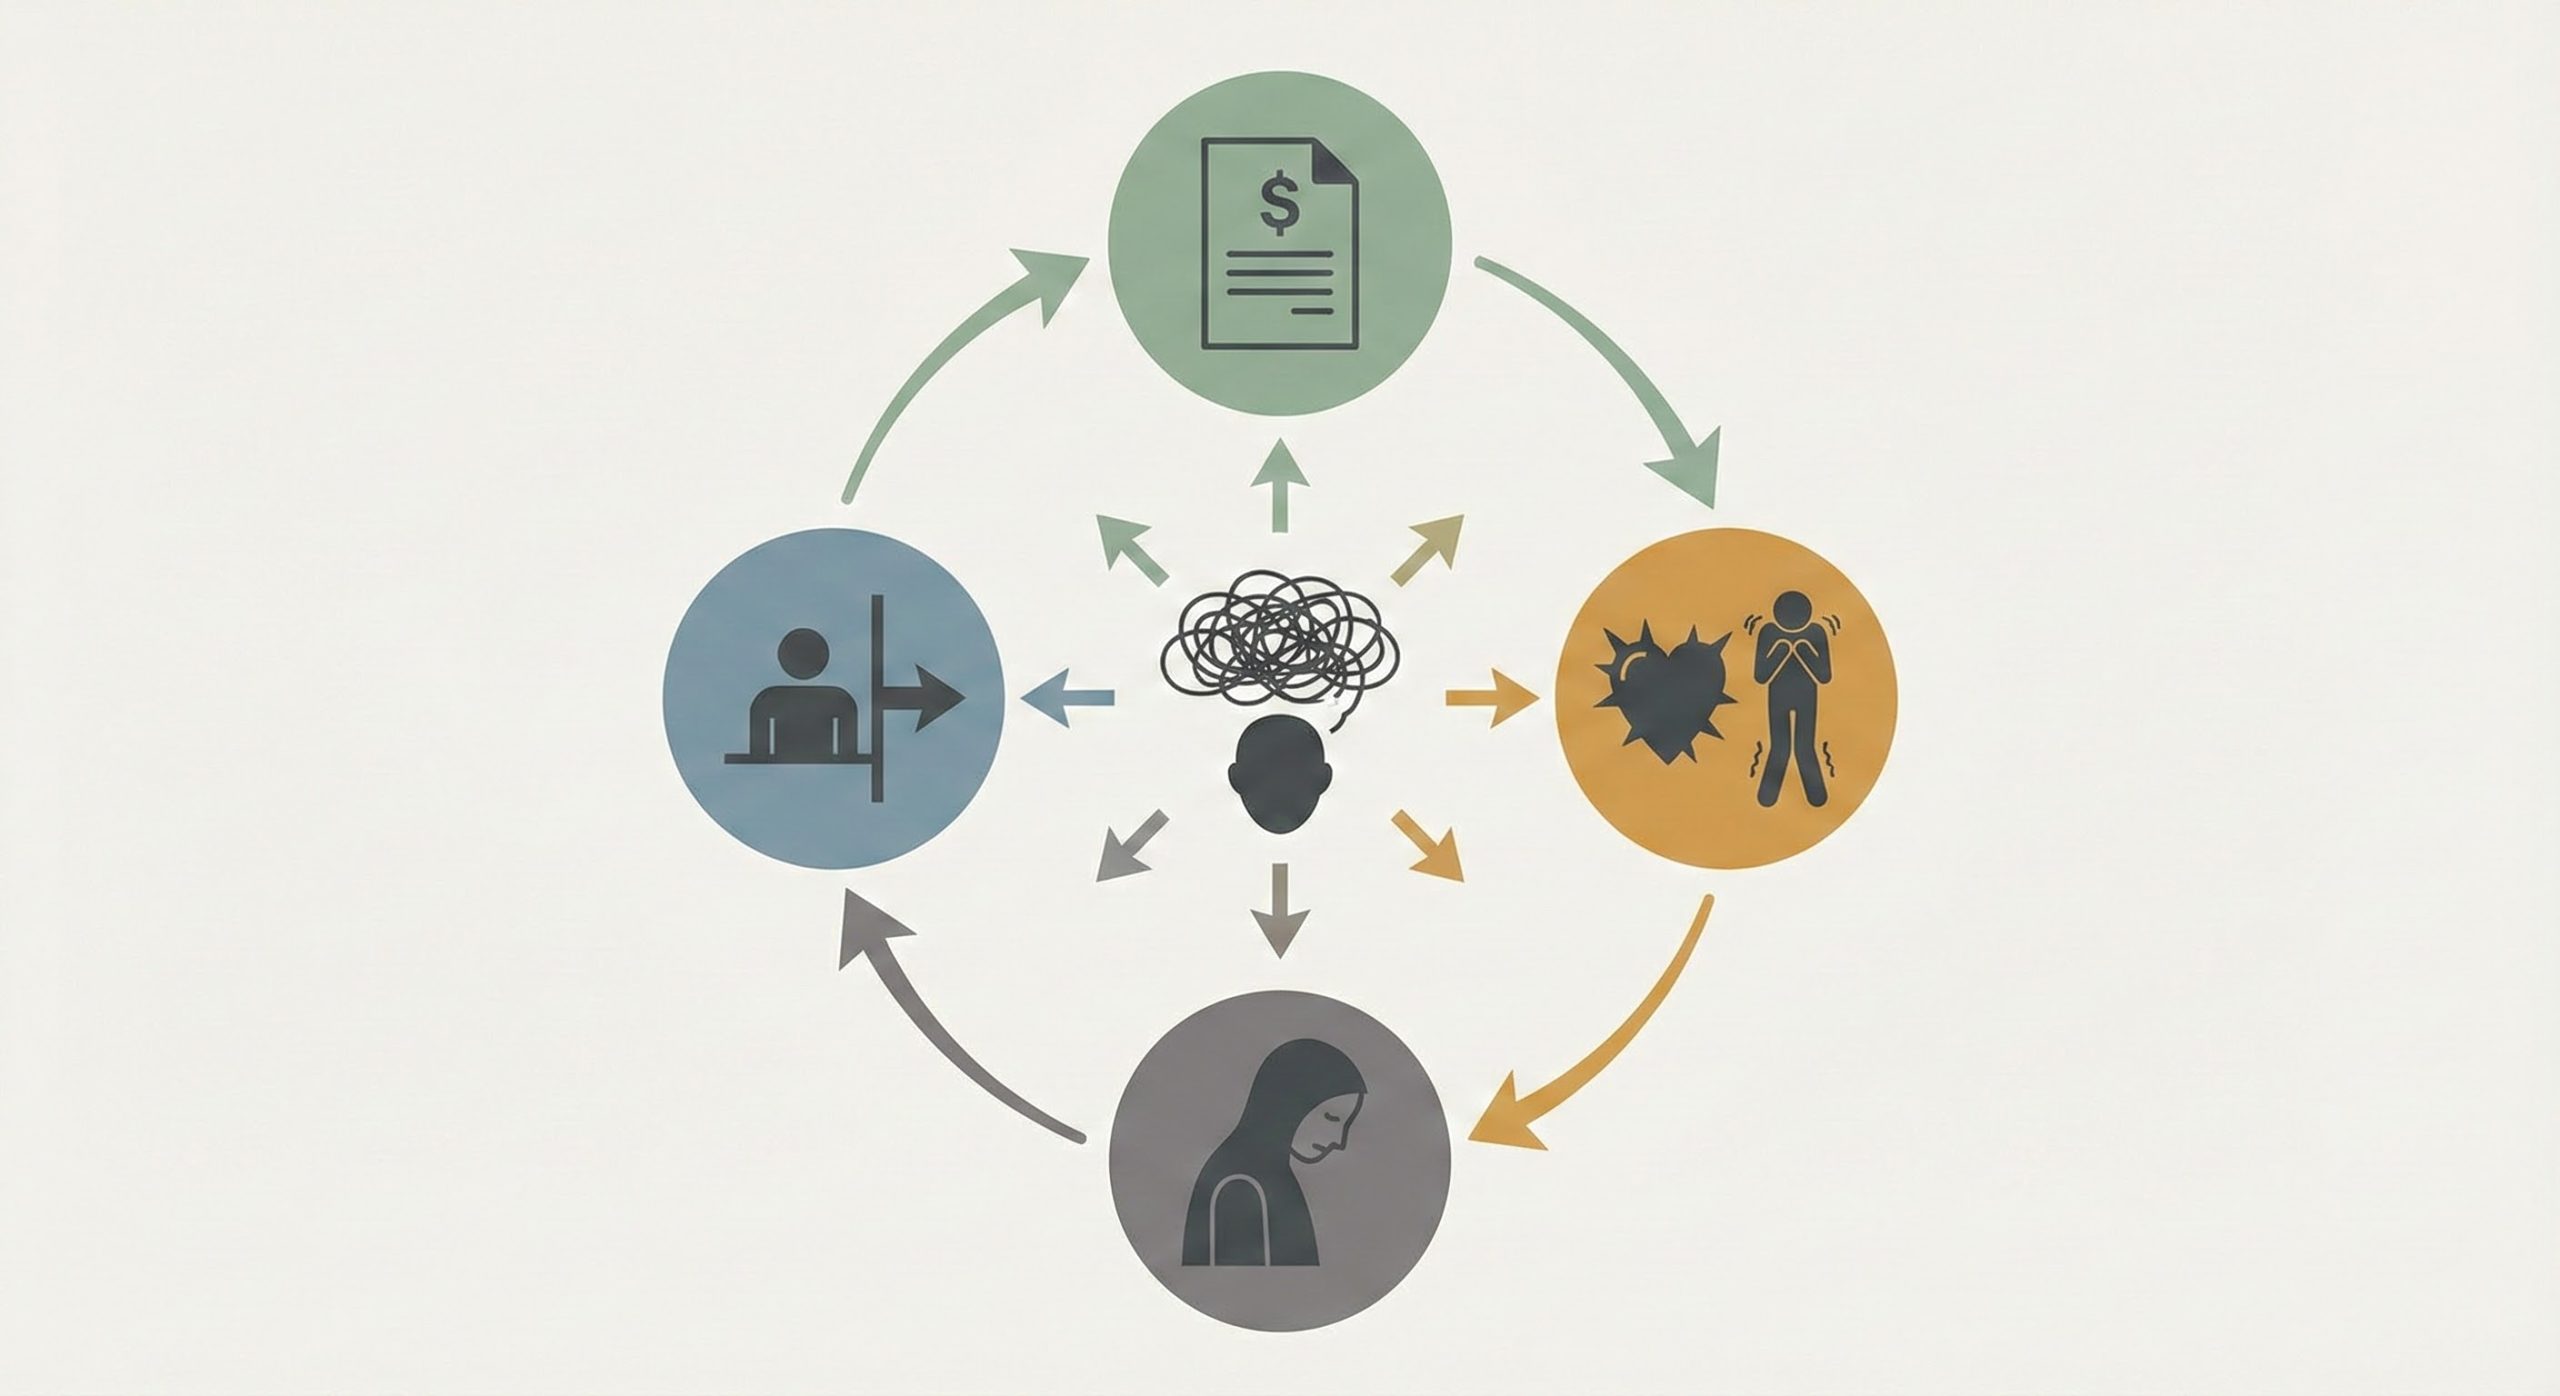
The Medical Debt Stress Loop
Medical debt stress often follows this pattern:
Bill arrives → fear & shame → avoidance → increased anxiety
Breaking this loop starts with calm engagement, not urgency.
What to Do—Without Shame or Panic
1️⃣ Pause Before You Act
Medical bills often feel urgent, but most are not emergencies.
Before taking action:
-
pause
-
take a few steady breaths
-
remind yourself that time and options usually exist
Calm decisions are better decisions.
2️⃣ Separate Emotion From Information
You don’t need to solve everything at once.
Start by understanding:
-
what the charge is for
-
what has already been paid or adjusted
-
what is still pending
Clarity reduces fear—even before anything changes.
3️⃣ Know That Options Often Exist
Many people don’t realize that:
-
payment plans are common
-
billing errors happen frequently
-
financial assistance programs may be available
Medical debt is often more flexible than it appears—but panic hides that fact.
4️⃣ Replace Catastrophic Thoughts
Thoughts like:
-
“This will ruin everything.”
-
“I’ll never recover from this.”
Increase stress without improving outcomes.
Try replacing them with:
“This is a problem I can address step by step.”
Language shapes emotional response.
5️⃣ Engage Gently, Not Perfectly
You don’t need a flawless plan.
Small steps matter:
-
opening one bill
-
making one call
-
asking one clarifying question
Progress builds confidence.
Medical Debt and Mental Well-Being
Ongoing medical debt stress can:
-
disrupt sleep
-
increase anxiety
-
discourage future care
-
reduce overall financial confidence
This is why medical debt is not just financial—it’s emotional.
Addressing stress improves outcomes.
When Support Is Helpful
If medical debt stress:
-
feels overwhelming
-
leads to ongoing avoidance
-
affects health decisions
Support—billing advocates, counselors, or trusted guidance—can restore calm and perspective.
Seeking help is not weakness. It’s self-protection.
Building Resilience After Medical Debt
Long-term calm doesn’t come from eliminating all risk.
It comes from:
-
understanding basic insurance concepts
-
maintaining a modest emergency buffer
-
trusting your ability to respond when needed
Resilience is about capacity, not certainty.
Gentle Reflection
-
What emotion shows up first when you think about medical debt?
-
Is that emotion tied to a past experience?
-
What would change if shame were removed from the equation?
Frequently Asked Questions
Is medical debt common?
Yes. Many people experience it at some point in their lives.
Does medical debt mean I failed financially?
No. It often reflects systemic healthcare costs—not personal choices.
Is it okay to take time before responding?
Yes. Calm engagement usually leads to better outcomes than urgency.
Final Thought
Medical debt feels heavy because it touches health, safety, and self-worth all at once.
But financial wellness doesn’t require perfection.
It requires clarity without shame.
When panic softens, options appear.
And when shame fades, calm action becomes possible.
Continue the Financial Wellness Series
This article is for educational purposes only and does not constitute medical or financial advice.
Sources
Consumer Financial Protection Bureau. Medical debt overview.
Kaiser Family Foundation. Medical debt and household financial health.
When to Seek Help
If medical debt feels unmanageable or emotionally overwhelming, seeking support from a certified financial counselor or nonprofit credit counseling organization is strongly recommended.

Michael Tran
Financial Wellness Editor at LifeWellToday
About Michael Tran
Michael Tran is a Financial Wellness Editor at LifeWellToday, where he focuses on the intersection of money, mental well-being, and everyday life.
His work helps readers understand financial stress not as a personal failure, but as a natural response to modern pressures—rising living costs, healthcare expenses, workplace demands, and economic uncertainty. Michael writes with a calm, human-centered approach, translating complex financial and insurance topics into practical, emotionally grounded guidance.
Rather than promoting hustle culture or extreme financial optimization, Michael emphasizes clarity, emotional safety, and sustainable habits. His goal is to help readers feel more confident and less overwhelmed when making everyday financial decisions.
Areas of Focus
- Money anxiety and emotional stress around finances
- Insurance literacy (health, life, and workplace coverage)
- Financial boundaries at work and burnout-related money stress
- Emergency funds, medical bills, and financial avoidance
- Behavioral finance and habit-based money systems
All content is written to align with responsible YMYL standards, prioritizing education, balance, and reader well-being.
Editorial Approach & Standards
At LifeWellToday, Michael collaborates closely with the editorial team to ensure that all Financial Wellness content:
- Is educational and informational—not personalized financial advice
- Reflects evidence-based insights from reputable sources
- Avoids fear-based or urgency-driven messaging
- Aligns with Google’s E-E-A-T (Experience, Expertise, Authoritativeness, Trustworthiness) guidelines
When appropriate, articles include references to trusted public sources and guidance on when readers should seek professional financial, medical, or mental health support.
Experience & Background
Michael has experience in editorial research and long-form content development within the lifestyle and wellness space. His background includes analyzing behavioral patterns, simplifying complex topics, and building content systems designed for clarity and reader trust.
He believes financial wellness is not about perfection or wealth—but about creating a sense of safety, agency, and self-respect around money.
Disclaimer
Michael Tran is not a licensed financial advisor, medical professional, or legal expert. All content published on LifeWellToday is intended for educational and informational purposes only and should not be considered professional advice.
Readers facing serious financial, medical, or mental health concerns are encouraged to consult qualified professionals.
Contact & Editorial Inquiries
For editorial questions or content-related inquiries, please contact:
? michael@lifewelltoday.com