


A calm, practical guide to picking health insurance without anxiety, jargon, or second-guessing
If choosing health insurance makes your chest tighten, you’re not alone.
Health insurance overwhelm is the anxiety people feel when complex plan choices, high stakes, and time pressure collide—making clear decisions feel impossible.
Pages of unfamiliar terms, conflicting advice, and the fear of “choosing wrong” can turn a necessary decision into a source of panic. The problem isn’t that you’re bad at insurance—it’s that most systems are designed around complexity, not clarity.
At LifeWellToday, we approach this as a Financial Wellness issue. When coverage feels confusing, your nervous system stays on high alert. This guide strips the process down to what actually matters—so you can choose coverage that supports your health and your peace of mind.
Why Health Insurance Feels So Overwhelming
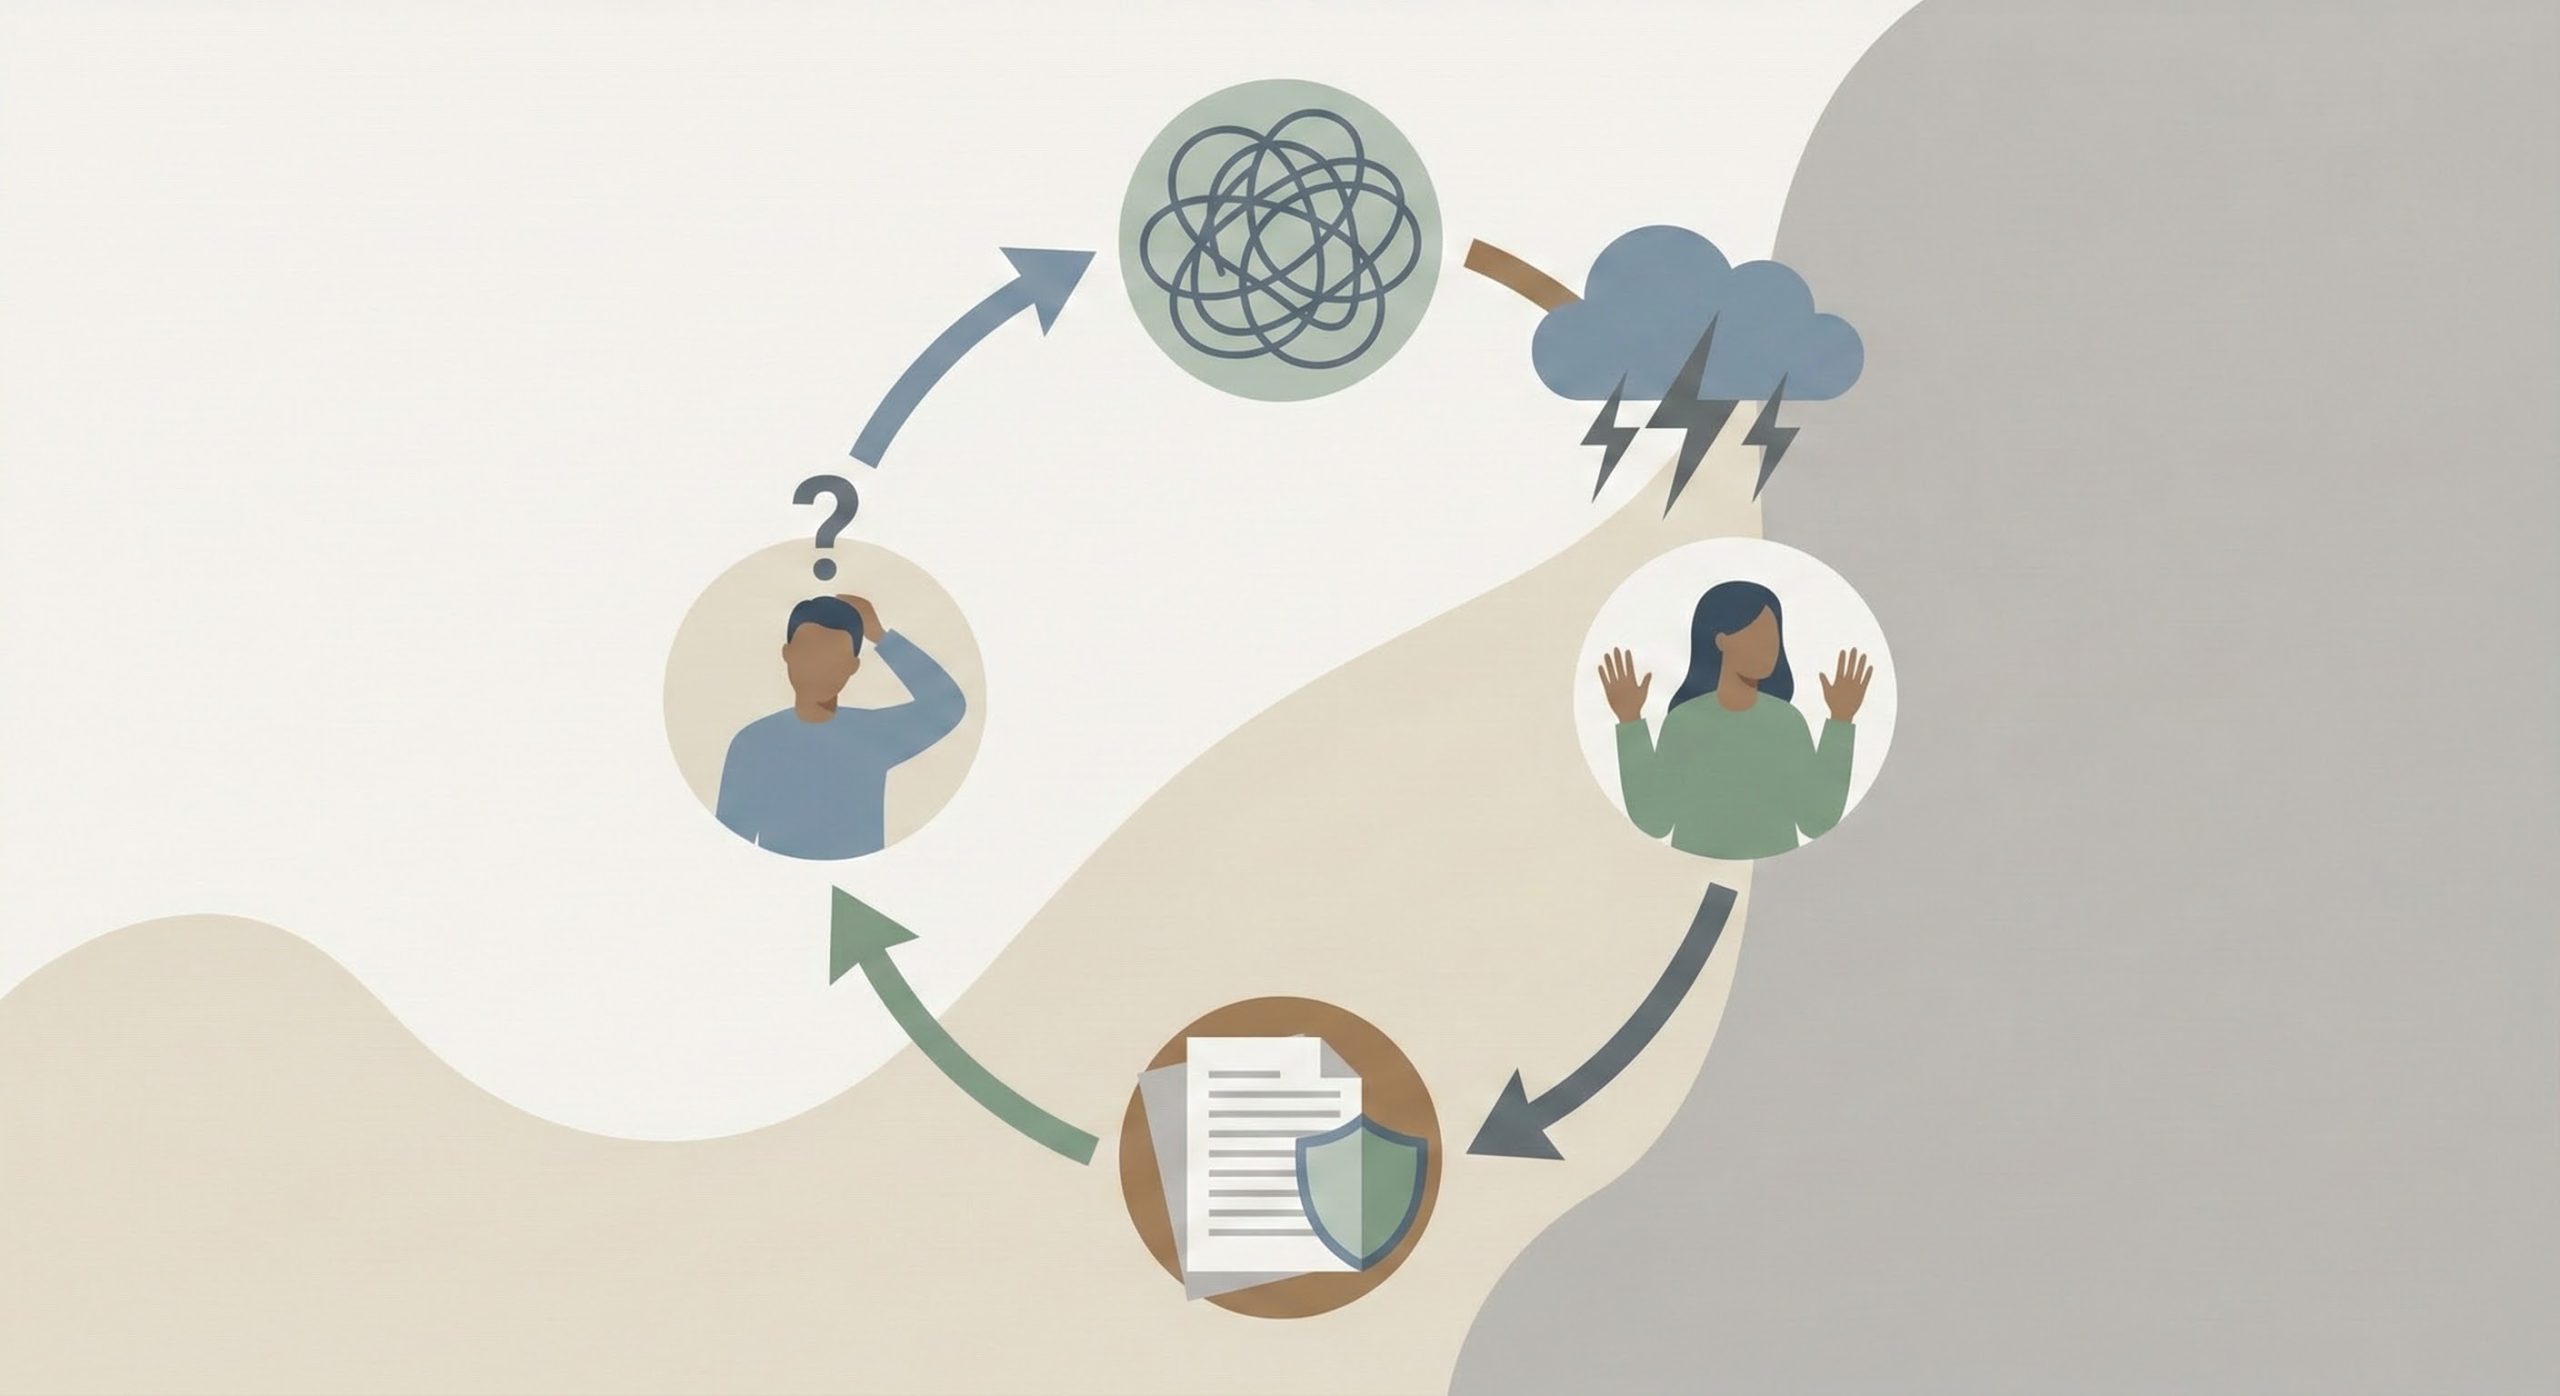
Insurance overwhelm usually comes from three forces working together:
-
Information density – too many plans, acronyms, and exceptions.
-
High stakes – the fear of medical bills and worst-case scenarios.
-
Time pressure – enrollment windows that force rushed decisions.
When stress rises, decision quality drops. The goal isn’t to find the “perfect” plan—it’s to find enough protection to feel safe.
Reframing the Goal: Coverage as Calm, Not Optimization
Most people approach insurance trying to optimize costs.
A calmer and more sustainable question is:
What level of coverage would help me sleep better this year?
Health insurance is a safety system, not a math competition. Start with emotional safety and predictability; cost efficiency comes second.
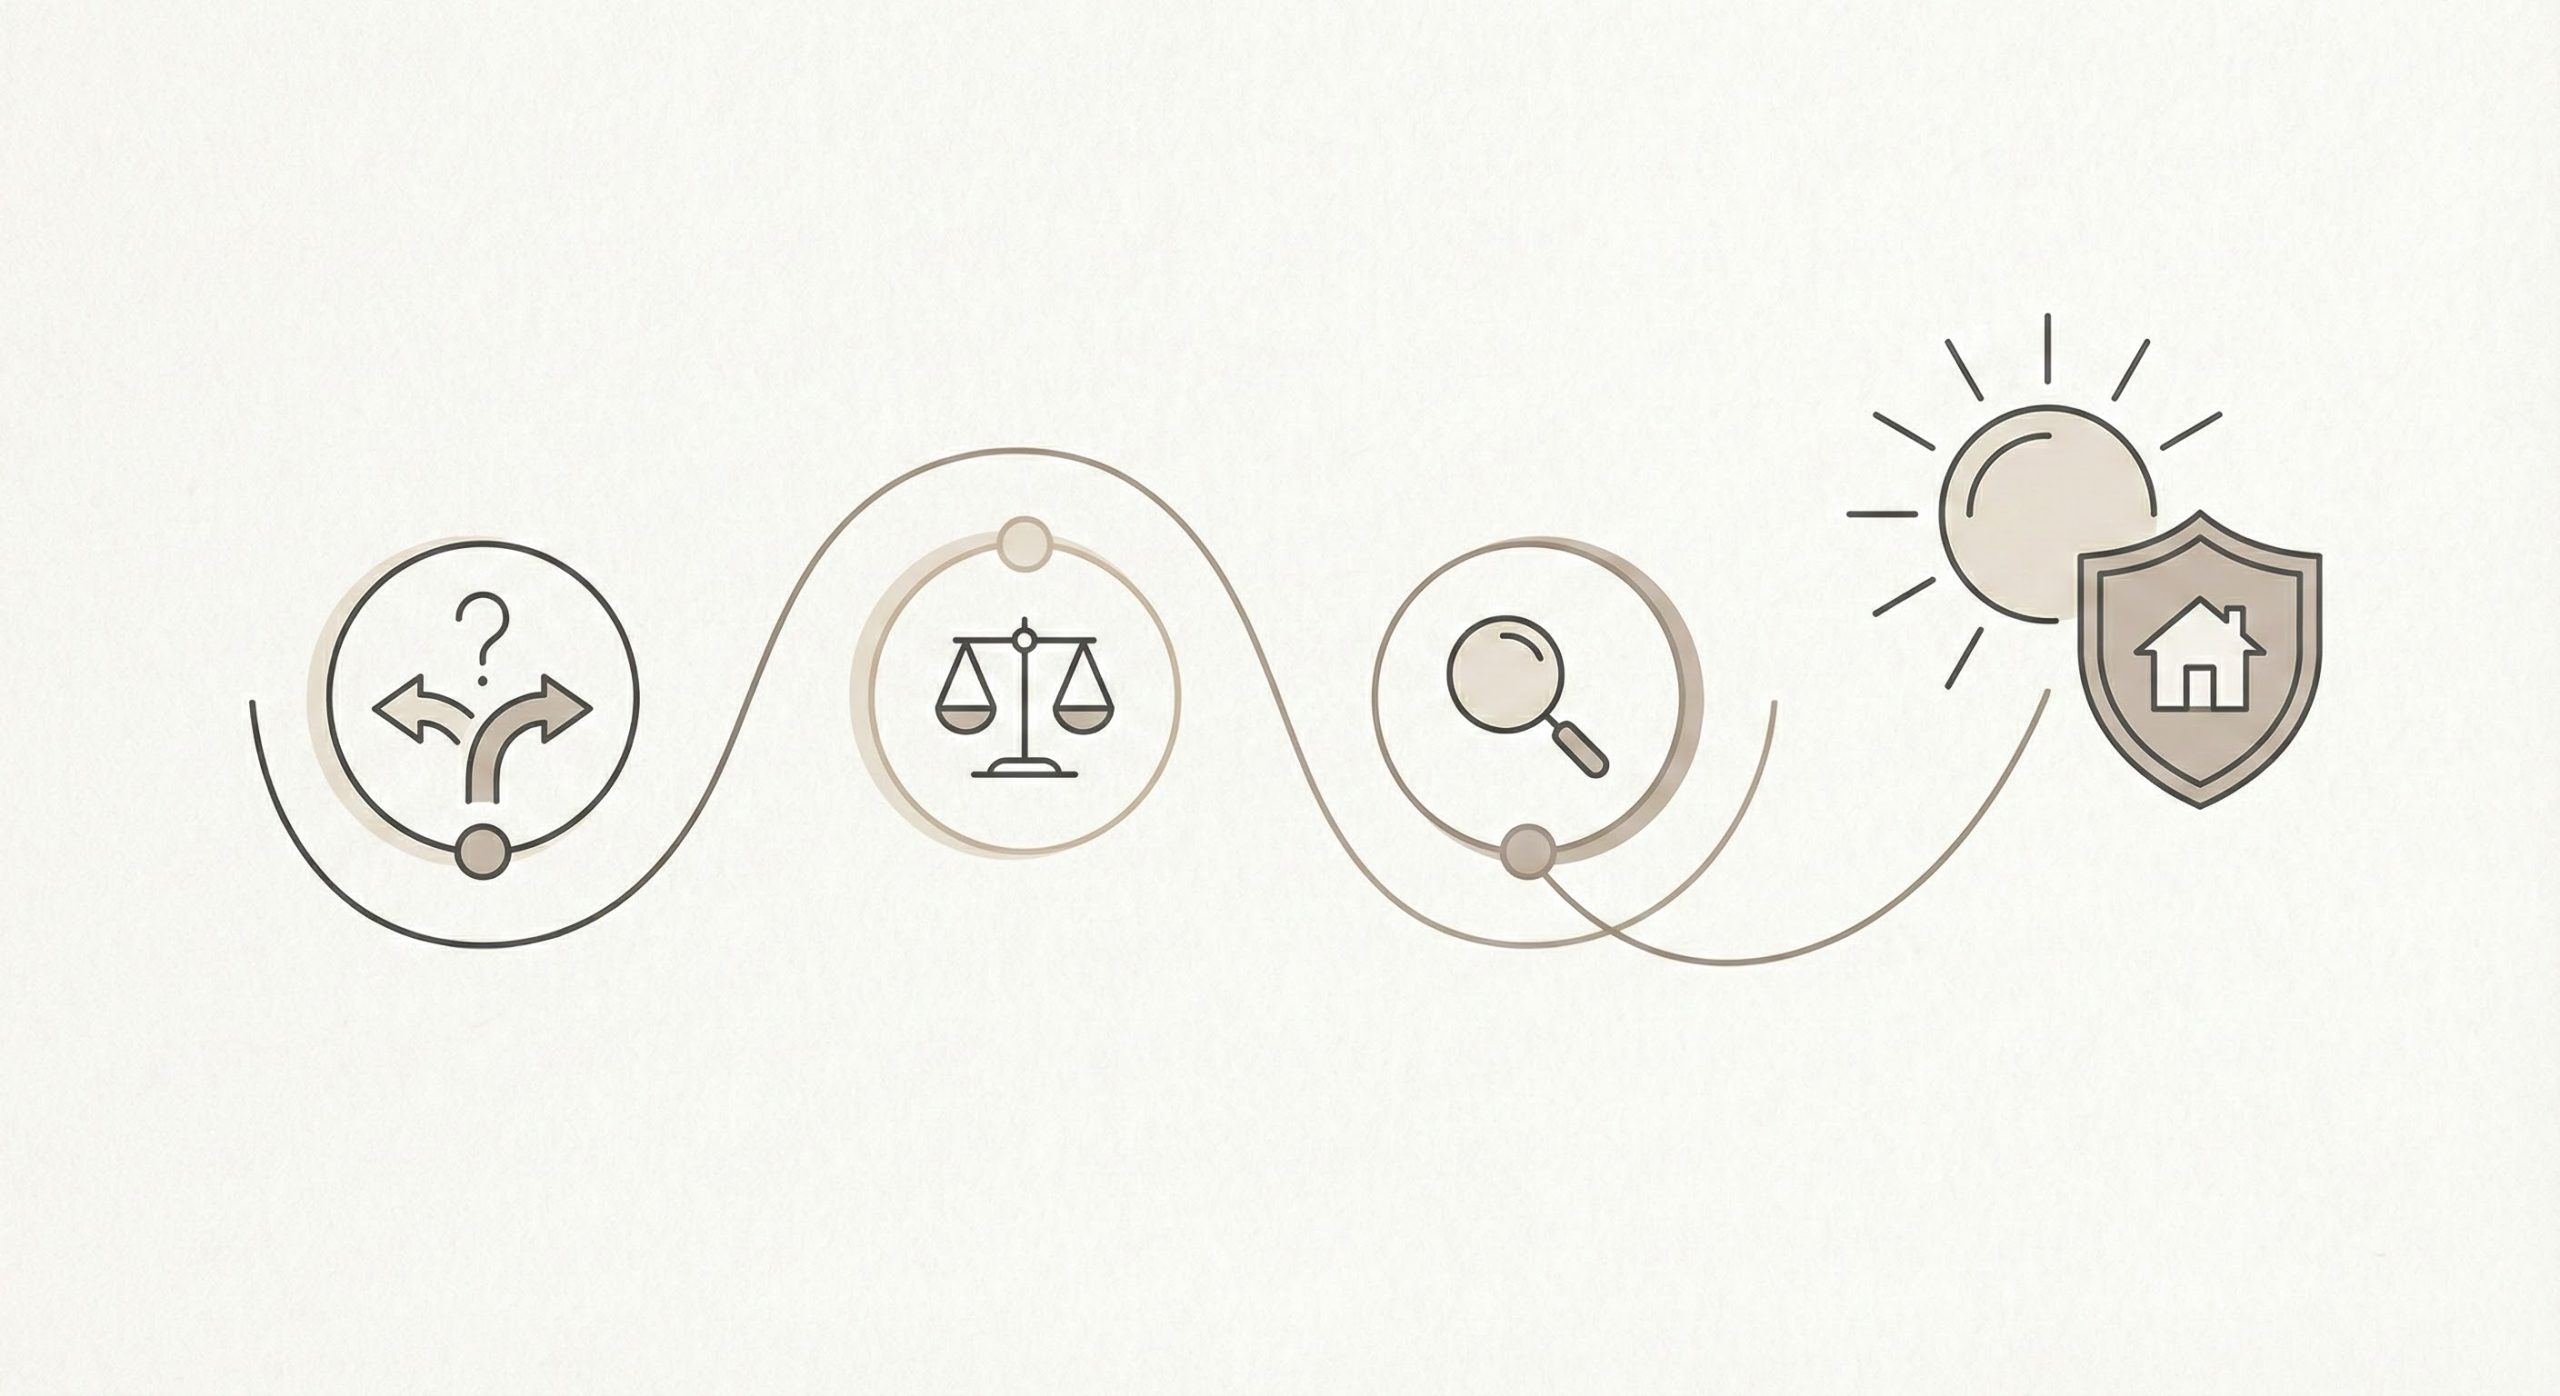
The Four Questions That Actually Matter
Ignore the noise and begin here.
1️⃣ What risks realistically apply to me this year?
Think about:
-
ongoing conditions or medications
-
likely life events (pregnancy, surgery, relocation)
-
mental health support needs
Coverage should reflect probability, not distant hypotheticals.
2️⃣ How much unpredictability can I tolerate?
This comes down to comfort with:
-
Deductibles (what you pay before coverage starts)
-
Out-of-pocket maximums (your true worst-case cost)
If financial uncertainty increases anxiety, prioritize a lower out-of-pocket maximum—even if premiums are higher.
3️⃣ Which doctors and services must stay accessible?
Check whether plans include:
-
your primary care provider
-
key specialists
-
mental health professionals
A cheaper plan that blocks access to care you already use often costs more—in stress and delays—than it saves.
4️⃣ How much administrative friction can I handle?
Some plans require more referrals, approvals, and paperwork.
If bureaucracy drains you, paying slightly more for simplicity and speed can be a form of self-care.
The Core Trade-Offs (Without Jargon)
Lower Premium vs. Lower Stress
-
Low premiums often mean higher deductibles and surprise costs.
-
Higher premiums often buy predictability and faster care.
Choose the structure that fits your stress tolerance, not just your budget.
Narrow Networks vs. Flexibility
-
Narrow networks can be cheaper—but restrictive.
-
Broader networks offer freedom and peace of mind.
Flexibility is a form of emotional safety.
A Calm Decision Framework
Instead of comparing everything at once:
-
Eliminate plans that don’t cover your non-negotiables.
-
From what remains, choose the plan with the clearest worst-case cost.
-
If you’re still unsure, choose the option that feels calmer, not cheaper.
Your body often recognizes safety before your spreadsheet does.
Common Mistakes That Increase Anxiety
-
choosing based only on monthly premium
-
underestimating mental health coverage
-
assuming “I won’t need it this year”
-
rushing decisions at the deadline
Calm decisions come from slowing down, even briefly.
Insurance as Financial Self-Care
Through a Financial Wellness lens, health insurance:
-
limits catastrophic financial risk
-
stabilizes future expenses
-
protects earning ability by supporting health
It isn’t a sunk cost—it’s preventive protection.
When It’s Okay to Ask for Help
You don’t need to navigate insurance alone.
It can be helpful to:
-
ask HR or benefits teams clarifying questions
-
use official marketplace support resources
-
talk through options with a licensed advisor—without pressure to decide immediately
Seeking clarity is a strength, not a failure.
If You’re Self-Employed or Freelance
Without employer coverage, anxiety often spikes.
Prioritize:
-
clearly defined coverage terms
-
manageable deductibles
-
predictable maximum costs
Consistency matters more than finding the “perfect” deal.
Gentle Reflection
-
Which health expenses would worry me most if they happened tomorrow?
-
Do I feel calmer with predictable monthly costs—or flexibility?
-
What plan would I trust myself not to avoid using?
Frequently Asked Questions
Is the cheapest plan always a bad idea?
Not always—but it can increase stress if high deductibles feel risky.
Should I change plans every year?
Only if your needs or risk tolerance change. Stability itself has value.
Can better coverage reduce financial anxiety?
Yes. Knowing your worst-case cost reduces mental load and fear.
Final Thought
You don’t need to master health insurance.
You need enough clarity to feel safe.
Choosing coverage without panic means shifting from fear-based decisions to calm, protective ones. When your plan reduces uncertainty and supports access to care, it’s doing its most important job—quietly.
Continue the Financial Wellness Series
-
Insurance Anxiety – why protection feels overwhelming
-
Emergency Fund Anxiety – finding enough without obsessing
-
Financial Wellness – The Calm Money Guide – building safety across your money life
This article is for educational purposes only and does not constitute medical, legal, or financial advice.
Sources
Healthcare.gov. Health insurance basics and coverage options.
Kaiser Family Foundation (KFF). Health insurance literacy resources.
When to Seek Help
For complex health insurance decisions or coverage concerns, a certified insurance navigator or licensed advisor can provide personalized guidance.

Michael Tran
Financial Wellness Editor at LifeWellToday
About Michael Tran
Michael Tran is a Financial Wellness Editor at LifeWellToday, where he focuses on the intersection of money, mental well-being, and everyday life.
His work helps readers understand financial stress not as a personal failure, but as a natural response to modern pressures—rising living costs, healthcare expenses, workplace demands, and economic uncertainty. Michael writes with a calm, human-centered approach, translating complex financial and insurance topics into practical, emotionally grounded guidance.
Rather than promoting hustle culture or extreme financial optimization, Michael emphasizes clarity, emotional safety, and sustainable habits. His goal is to help readers feel more confident and less overwhelmed when making everyday financial decisions.
Areas of Focus
- Money anxiety and emotional stress around finances
- Insurance literacy (health, life, and workplace coverage)
- Financial boundaries at work and burnout-related money stress
- Emergency funds, medical bills, and financial avoidance
- Behavioral finance and habit-based money systems
All content is written to align with responsible YMYL standards, prioritizing education, balance, and reader well-being.
Editorial Approach & Standards
At LifeWellToday, Michael collaborates closely with the editorial team to ensure that all Financial Wellness content:
- Is educational and informational—not personalized financial advice
- Reflects evidence-based insights from reputable sources
- Avoids fear-based or urgency-driven messaging
- Aligns with Google’s E-E-A-T (Experience, Expertise, Authoritativeness, Trustworthiness) guidelines
When appropriate, articles include references to trusted public sources and guidance on when readers should seek professional financial, medical, or mental health support.
Experience & Background
Michael has experience in editorial research and long-form content development within the lifestyle and wellness space. His background includes analyzing behavioral patterns, simplifying complex topics, and building content systems designed for clarity and reader trust.
He believes financial wellness is not about perfection or wealth—but about creating a sense of safety, agency, and self-respect around money.
Disclaimer
Michael Tran is not a licensed financial advisor, medical professional, or legal expert. All content published on LifeWellToday is intended for educational and informational purposes only and should not be considered professional advice.
Readers facing serious financial, medical, or mental health concerns are encouraged to consult qualified professionals.
Contact & Editorial Inquiries
For editorial questions or content-related inquiries, please contact:
? michael@lifewelltoday.com
2 Comments
Pingback: Medical Debt Stress: What to Do Without Shame or Panic
Pingback: Medical Bills Anxiety: Preparing Without Living in Fear